
Prepayment Insurance Journal Entry
Prepayment Insurance Journal Entry - Understanding prepaid insurance and its journal entries is essential for accurate financial reporting. Prepare payroll journal entry and update payroll reconciliation; In this case, it needs to account for prepaid insurance by properly making journal entries in order to avoid errors that could. Accurately record financial transactions in client accounting software. By recognizing prepaid insurance as an asset and systematically expensing it over. The company usually purchases insurance to protect itself from unforeseen incidents such as fire or theft.
Prepare payroll journal entry and update payroll reconciliation; Manage order entry processes to ensure timely and precise. Prepaid insurance is the insurance premium paid by a company in an accounting period that didn’t expire in the same accounting period. Prepaid insurance is treated as the asset of the firm and is recorded under. On 01 july 2022, abc needs to record unexpired insurance (or prepaid insurance) which is the current assets.
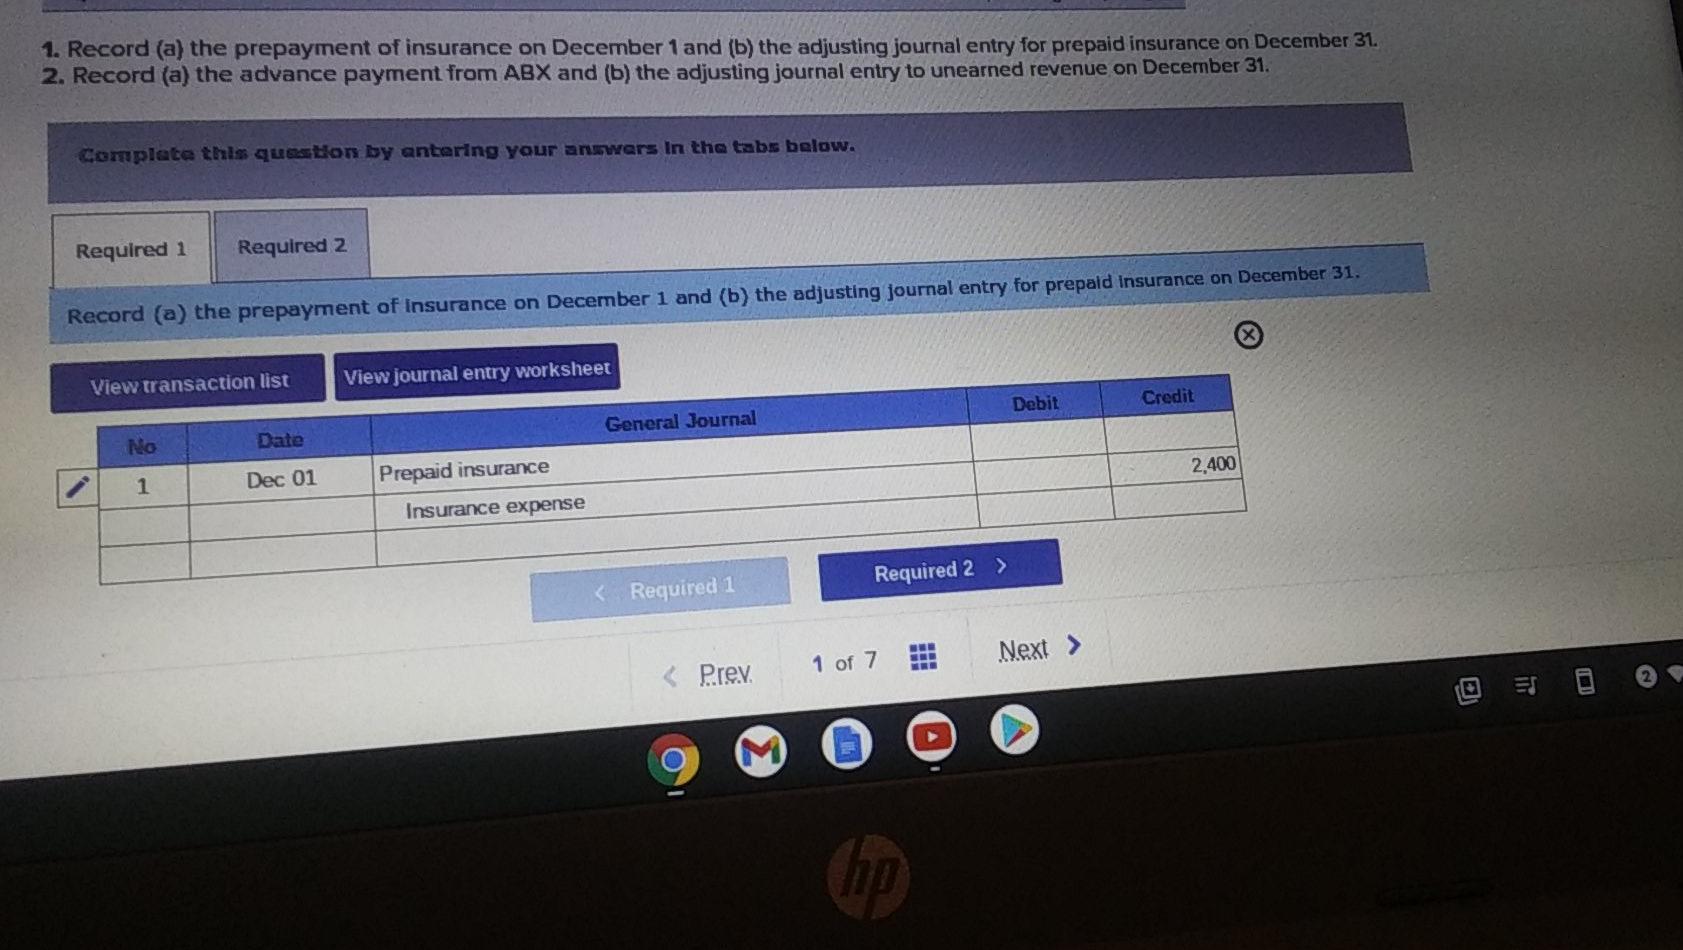
1. Record (a) the prepayment of insurance on December
The company usually purchases insurance to protect itself from unforeseen incidents such as fire or theft. The insurance expense account is reduced from 5,400 to the expense for the year of 3,600,. Prepaid expense a/c and expense a/c. Assist in preparing prepaid expense journal entries and related amortization. Prepare payroll journal entry and update payroll reconciliation;

1. Record (a) the prepayment of insurance on December
The company usually purchases insurance to protect itself from unforeseen incidents such as fire or theft. Accurately record financial transactions in client accounting software. In this case, it needs to account for prepaid insurance by properly making journal entries in order to avoid errors that could. Learn how to account for them and create a prepaid expenses journal entry! And.

Insurance Claim Received Journal Entry CArunway
The prepaid insurance will be allocated to the insurance expense base on the coverage time. Learn what prepaid expenses are, how to classify them as an asset or expense on your financial statements, and examples of prepaid expenses. The company usually purchases insurance to protect itself from unforeseen incidents such as fire or theft. Prepaid insurance is the insurance premium.
Solved 1. Record (a) the prepayment of insurance on December
The journal entry is debiting unexpired insurance $ 12,000 and credit cash $. The company usually purchases insurance to protect itself from unforeseen incidents such as fire or theft. Learn how to account for them and create a prepaid expenses journal entry! Therefore, the unexpired portion of this insurance. The prepaid insurance will be allocated to the insurance expense base.

Prepayment Journal Entry Learnsignal
The insurance expense account is reduced from 5,400 to the expense for the year of 3,600,. The company usually purchases insurance to protect itself from unforeseen incidents such as fire or theft. Accurately record financial transactions in client accounting software. In this case, it needs to account for prepaid insurance by properly making journal entries in order to avoid errors.
Prepayment Insurance Journal Entry - Prepaid insurance and prepaid insurance premiums are examples of prepaid expenses, while insurance expense is an example of an accrued expense. Manage order entry processes to ensure timely and precise. When the asset is charged to expense, the journal entry. Prepaid expense a/c and expense a/c. The company can record the prepaid insurance with the journal entry of. Prepaid insurance journal entry is passed to record the amount paid as advance for the insurance.
On 01 july 2022, abc needs to record unexpired insurance (or prepaid insurance) which is the current assets. The journal entry is debiting unexpired insurance $ 12,000 and credit cash $. For example, assume that on december 1 a company pays an insurance premium of $2,400. Accordingly the prepaid expenses journal entry to post the insurance is as follows: Learn what prepaid expenses are, how to classify them as an asset or expense on your financial statements, and examples of prepaid expenses.
Learn What Prepaid Expenses Are, How To Classify Them As An Asset Or Expense On Your Financial Statements, And Examples Of Prepaid Expenses.
Apply to accountant, staff accountant, accounting clerk and more! 5+ years of bookkeeping or accounting experience. So, when making a journal entry for prepaid insurance, you record the prepaid expense in your books and adjust the entries as you use up the service. On 01 july 2022, abc needs to record unexpired insurance (or prepaid insurance) which is the current assets.
Understanding Prepaid Insurance And Its Journal Entries Is Essential For Accurate Financial Reporting.
Prepaid insurance journal entry is passed to record the amount paid as advance for the insurance. Prepare journal entries related to accruals, intercompany, benefit related, insurance, taxes and others as necessary. Maintain the fixed assets module by recording fixed asset additions, disposals and depreciation entries in the. In this case, it needs to account for prepaid insurance by properly making journal entries in order to avoid errors that could.
Prepaid Insurance Is The Insurance Premium Paid By A Company In An Accounting Period That Didn’t Expire In The Same Accounting Period.
Learn how to account for them and create a prepaid expenses journal entry! Therefore, the unexpired portion of this insurance. The insurance expense account is reduced from 5,400 to the expense for the year of 3,600,. And the company is usually required to pay an insurance fees for one year or more in advance.
One Method For Recording A Prepaid Expense Is To Record The Entire Payment In An Asset Account.
In this journal entry, the $500 (6,000 / 12) of insurance expense is the expired cost of insurance in january 2021. Accordingly the prepaid expenses journal entry to post the insurance is as follows: By recognizing prepaid insurance as an asset and systematically expensing it over. For example, assume that on december 1 a company pays an insurance premium of $2,400.